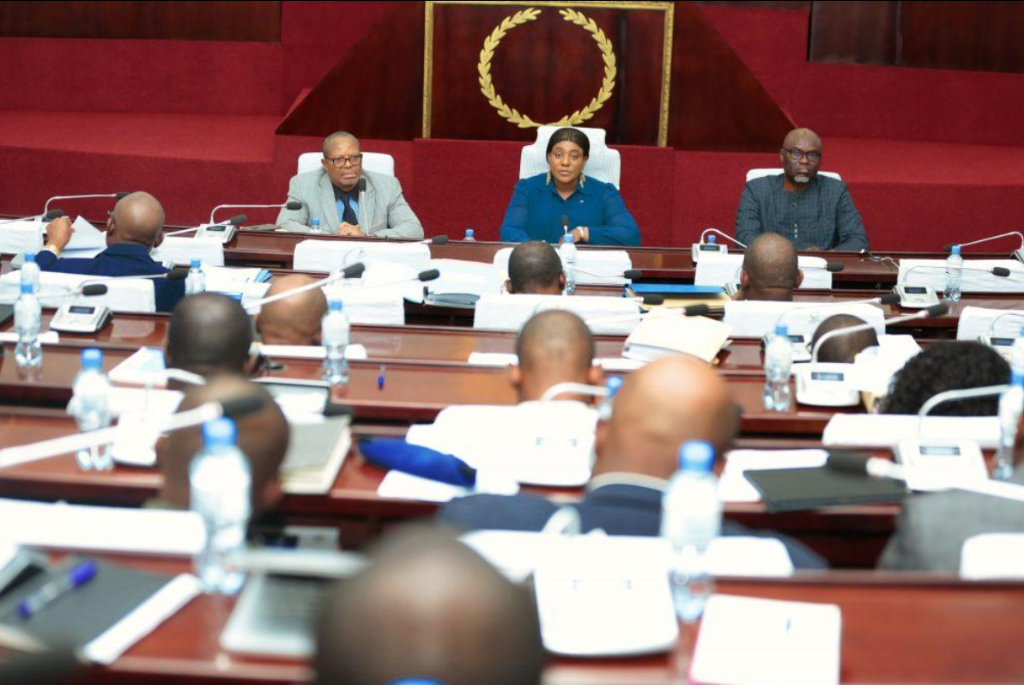
With a public debt ratio of 60.2% of GDP as of June 2026, Togo remains below the 70% ceiling set by the West African Economic and Monetary Union (WAEMU). Yet this 9.8-point buffer disguises deeper challenges—escalating debt servicing costs and mounting state financing needs are tightening the noose around the country’s fiscal maneuverability. The question is no longer just about reaching the community-imposed limit, but about whether further borrowing will further strain public finances instead of fueling sustainable growth.
Beyond the 70% ceiling: what hides behind the numbers
At first glance, the drop from 62.8% at the end of 2025 to 60.2% in mid-2026 suggests progress. However, this is only relative. In absolute terms, central government debt rose by 3.4%, from 4,312.6 billion FCFA to 4,458.1 billion FCFA. The decline in the debt-to-GDP ratio is largely due to faster nominal GDP growth rather than actual debt reduction.
The WAEMU’s 70% benchmark serves as a warning system, not a red line. Crossing it triggers stricter oversight and triggers corrective mechanisms. But the real danger lies not in hitting the threshold itself, but in what it exposes: limited fiscal bandwidth, higher borrowing costs, and reduced room for maneuver during economic shocks.
Why short-term debt is tightening the fiscal squeeze
The structure of Togo’s debt is becoming less favorable over time. In 2024, the weighted average maturity of regional bond issuances plummeted to just 1.5 years from seven years in 2022. More critically, short-term Treasury bills accounted for 71% of newly issued debt in 2024—up from just 5% in 2021–2022. This means the state is increasingly forced to refinance high volumes of debt under volatile market conditions.
By the end of 2025, outstanding payment arrears had risen to 0.6% of GDP, revealing a liquidity crunch. Every refinancing requirement diverts resources away from development projects and social spending. The more the state borrows to pay existing debt, the more interest consumes a larger share of the budget—creating a dangerous feedback loop.
Why Togo is shifting toward external concessional loans
Faced with shrinking margins on the regional market, the government is recalibrating its borrowing strategy. The new plan emphasizes concessional loans from multilateral partners—offering longer repayment terms and lower interest rates than regional issuances. These loans provide breathing space: deferred repayments and grace periods allow for better cash-flow planning and reduce the risk of rollover crises.
Yet external borrowing is no magic bullet. All new debt—whether from the World Bank, the African Development Bank, or regional markets—still counts toward the 70% ceiling. Diversifying sources does not automatically reduce debt levels; it only changes their cost profile and liquidity risk.
Togo’s 2026 borrowing plan envisages 650.7 billion FCFA in external financing and 486.1 billion FCFA in domestic issuance—386.1 billion from WAEMU bonds. This mix reflects a deliberate effort to balance cost, duration, and risk, not to abandon regional markets altogether.
The real test: does borrowing still fund growth—or just debt?
The IMF classifies Togo’s debt as sustainable, but warns that fiscal buffers are thin. Sustainability is not just about staying below 70%. It’s about ensuring new borrowing generates enough economic returns and fiscal revenue to cover its own cost. If loans finance unproductive projects or miss disbursement deadlines, the debt burden will outgrow the benefits.
For Togo, the core challenge is not how much more it can borrow, but whether every new naira generates value. The goal must be a borrowing policy that funds infrastructure, education, and healthcare without siphoning off future revenue into interest payments. Otherwise, the debt ceiling becomes less a safeguard and more an outcome of unsustainable fiscal choices.
Key takeaways for policymakers and citizens
- Debt growth ≠ fiscal progress: Even as the ratio falls, absolute debt is rising—masking underlying pressure.
- Short-term traps: High refinancing risk and low average maturity make the debt profile more fragile.
- External shifts: Concessional loans can ease liquidity but do not eliminate ceiling constraints.
- Investment check: Every new loan must prove its return or risk shifting public funds to debt service instead of development.